The Truth About Debt Service Coverage Ratio (DSCR): How It's Actually Calculated
- DSCR = cash flow available for debt service ÷ required debt payments.
- Use the same period for income and debt payments.
- Cash-flow adjustments need supporting records and lender acceptance.
Debt service coverage ratio (DSCR) compares cash flow available for debt service with the debt payments due over the same period. A ratio of 1.00 means those amounts are equal. Lenders use their applicable cash-flow definitions, permitted adjustments and coverage requirements to evaluate repayment capacity.
A lender must establish reasonable repayment ability. A tax-return loss is not the same as cash available for debt service, but a score or an accounting addback does not remove the need to support repayment. Adjustments must be documented and accepted by the lender. E-Tran is SBA’s electronic loan-processing system, not a universal borrower score. Under SBA’s March 1, 2026 notice, SBA no longer screens or assigns FICO SBSS scores for 7(a) Small applications. Lenders still review credit and repayment ability and may use permitted scoring models. See our E-Tran and SBSS guide.
What is DSCR?
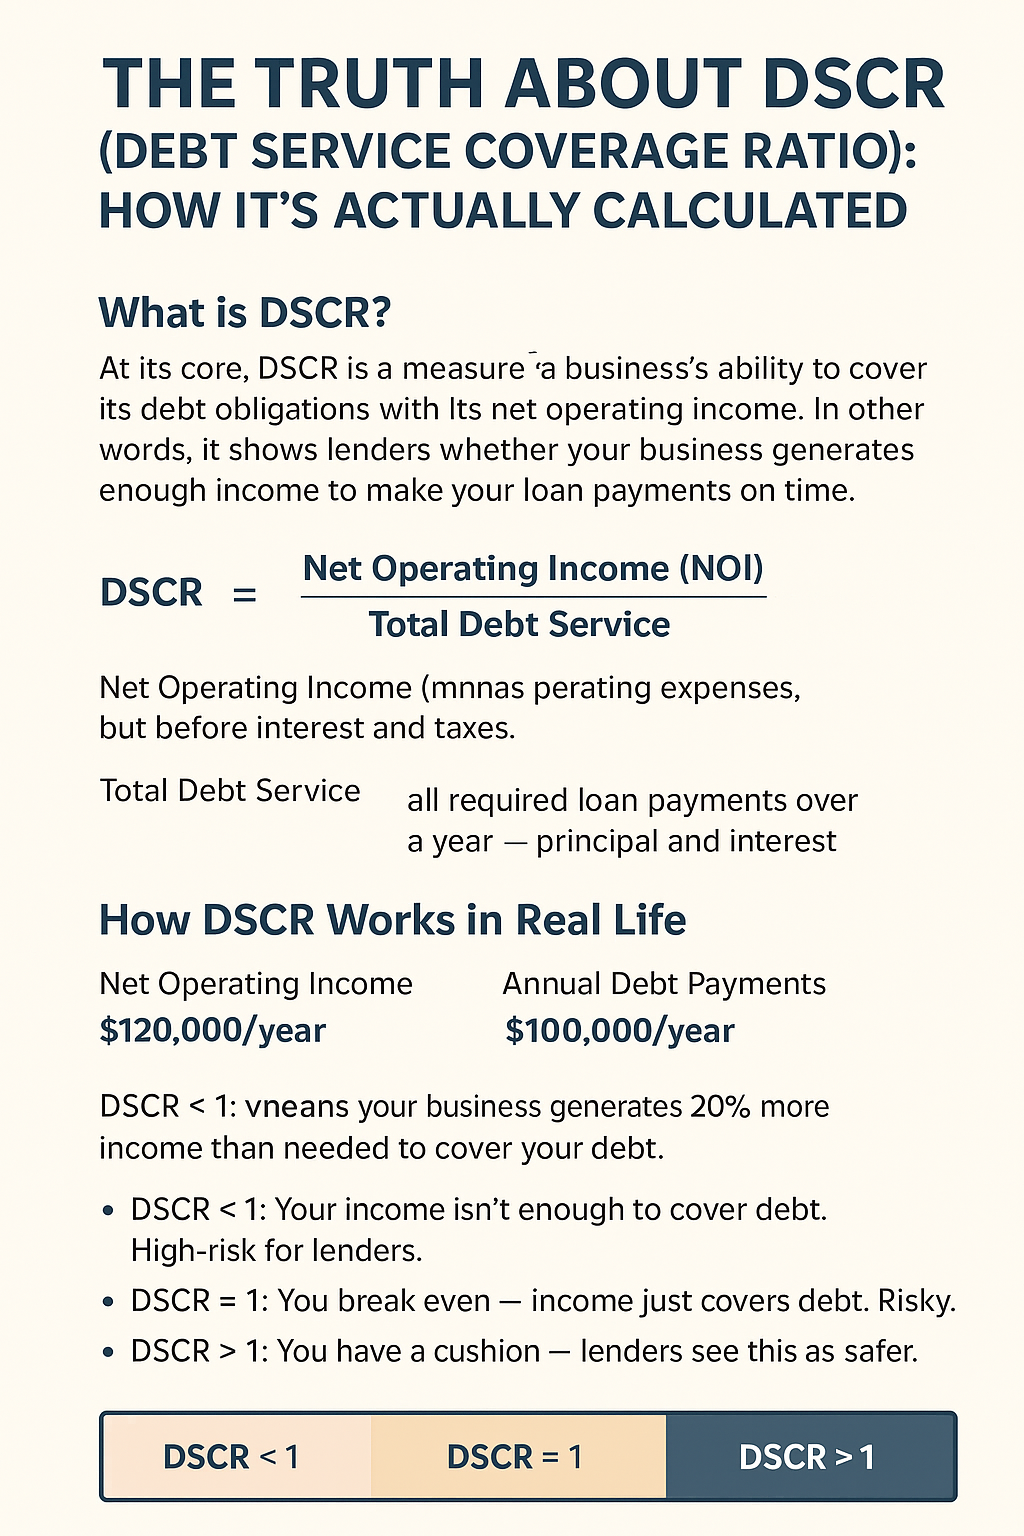
At its core, DSCR is a measure of a business’s ability to cover its anticipated loan debt obligations with its net operating income. In other words, it shows lenders whether your business generates enough income to make your anticipated loan payments on time. The lender wants to ensure that the business will be able to cover expected loan payments.
DSCR Formula:
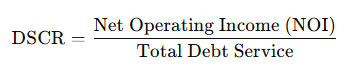
Net Operating Income (NOI): This is your business revenue minus operating expenses, but before interest and taxes.
Total Debt Service: This includes all required loan payments over a year - principal and interest.
Example of How DSCR Works
Here’s a simple example:
- Net Operating Income: $120,000/year
- Annual Debt Payments: $100,000/year
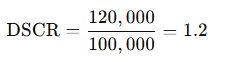
A DSCR of 1.2 means your business generates 20% more income than needed to cover your debt. Lenders typically look for a DSCR of 1.25 or higher, depending on the type of loan and risk profile.
DSCR < 1: Your income isn’t enough to cover debt. High-risk for lenders.
DSCR = 1: You break even — income just covers debt. Risky.
DSCR > 1: You have a cushion — lenders see this as safer.
Common Misconceptions About Debt Service Coverage Ratio (DSCR)
- DSCR compares lender-accepted operating cash flow with required debt service for the same period. Depreciation is a non-cash expense, not a tax liability; any addback must be supported. Owner pay is not automatically added back.
- Lenders calculate it differently: Some lenders adjust NOI to exclude one-time income or expenses, giving a more realistic picture of repayment ability.
- Higher isn’t always better: While a higher DSCR shows safety, it can also indicate higher approval amounts - your business might be able to take on more debt to fuel growth.
- DSCR requirements vary by program, use of proceeds and lender. A high SBSS score does not create a universal exemption from repayment analysis.
Why DSCR Matters for SBA Loans
For SBA 7(a) loans, DSCR is a key underwriting metric:
- SBA 7(a) loans: Typically require a DSCR of at least 1.15, this is determined by the bank. Each bank has a minimum required DSCR for approval.
Meeting the DSCR requirement doesn’t just help you qualify — it can also secure better interest rates and terms.
Tips to Improve Your DSCR
- Increase net operating income: Boost revenue, reduce operating costs, or streamline expenses.
- Refinance high-interest debt: Lower payments improve your debt service ratio.
- Delay new debt: Avoid taking on additional loans until your DSCR is strong.
- Consider a larger down payment: Reduces debt service and increases DSCR.
DSCR Not Always Required
DSCR may sound complicated, but at its core, it’s a simple measure of whether your business can cover anticipated debt payments. By understanding how it’s calculated and what lenders are looking for, you can position your business for better financing terms and smarter borrowing decisions. One of the many benefits of working with FastWaySBA is our vast knowledge of which banks will approve your business based on your business’ DSCR.
Work through your own cash-flow inputs
Use the debt service coverage ratio calculator to explore the relationship between income and debt service. Keep losses visible and document any proposed adjustments before discussing the result with your lender.